Hello to all our clients,
Welcome to the October newsletter.
As we move into October, we wish to thank everyone who has already sent through their records and information.
If you haven’t yet, we’d really appreciate receiving your information as soon as you are able.
Receiving your records early helps us plan our workflow, complete your accounts efficiently, and return your completed financial statements and tax work to you in a timely manner.
It also gives us more opportunity to discuss any questions or planning opportunities before key deadlines.
As always, thank you for your continued support, if you have any questions or need assistance, please don’t hesitate to get in touch.
Information from the KTS office
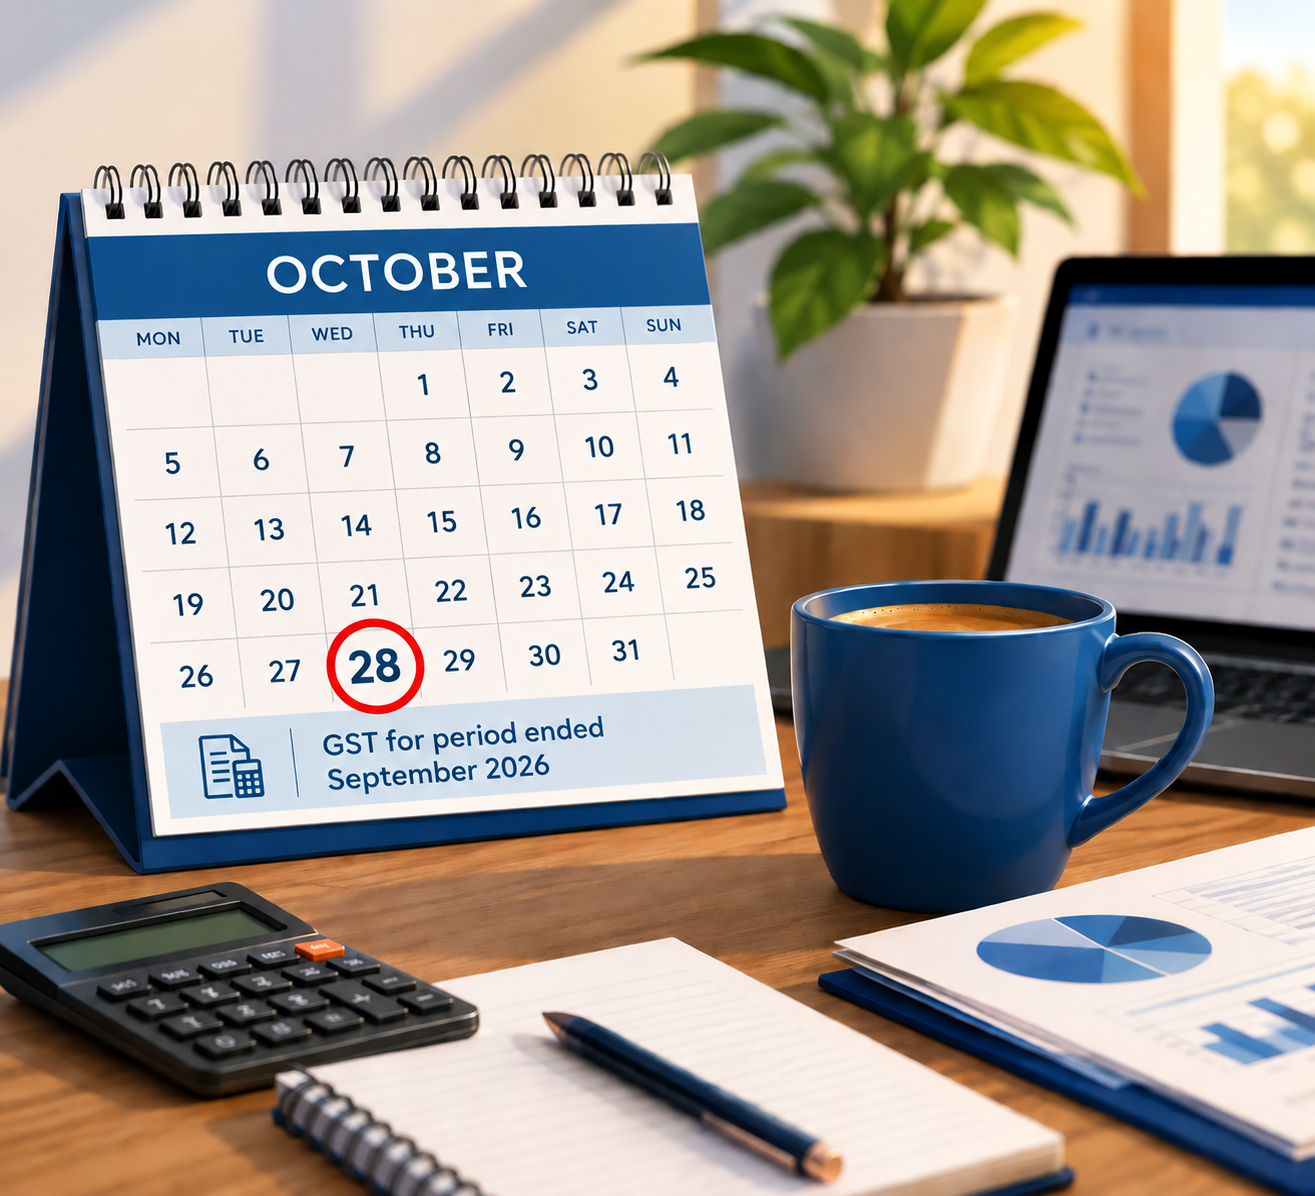
Tax payments due 28 October 2026
GST return and payment for the period ended 30 September 2026.
This GST payment date applies to both two-monthly and six-monthly GST filers.
Provisional tax is also due if you file your GST on a six monthly basis.
Please ensure your GST information is provided to us in plenty of time for your return to be completed.
Changes to your business
Are you thinking about making changes to your business?
Whether you’re considering changing your business structure, bringing in a new shareholder or partner, buying or selling part of the business, or making another significant change, it’s a good idea to talk to us first.
Business changes can sometimes have unexpected tax or GST implications.
A quick discussion with your accountant before you make any decisions can help you understand the implications and make sure the change is structured in the best way for you.
If you’re considering any changes, please get in touch with us – we’re happy to talk through your plans and help you work out the best way forward.
Other updates of interest to clients
Overhaul of Fringe Benefit Tax for vehicles
Starting 1 April 2027, the way Fringe Benefit Tax (FBT) is calculated for staff and shareholder vehicles, is getting a massive shake-up.
The best part is you won’t have to meticulously track and measure exactly how much vehicles are for private use. Instead, your FBT obligation will be determined by how the vehicle is mainly used.
At this stage we don’t know what is meant by “mainly” or what evidence will be required to support that, but there will undoubtedly be specific guidance soon and we will cover that when available.
The new rules sort company vehicles into six usage categories, each with a specific ‘inclusion rate”
Health and Safety Benefits – When does FBT Apply?
Some benefits provided to employees for health and safety reasons can be exempt from Fringe Benefit Tax (FBT).
However, not every health or wellbeing expense will qualify.
For the exemption to apply, the benefit generally needs to meet certain requirements:
Tax-free commuting via salary sacrifice
Employers can offer staff a tax-efficient way to purchase or lease bicycles, e-bikes and e-scooters for commuting, with payments made from their pre-tax salary.
There can be worthwhile tax benefits for both the employer and employee.
However, salary sacrifice arrangements need to be structured correctly to meet Inland Revenue requirements.
Talk to us first
While these schemes can offer useful tax savings, changing an employee’s remuneration package involves tax, payroll and employment considerations.
If the arrangement is not set up correctly, Inland Revenue may treat the salary deductions as ordinary taxable income, potentially resulting in additional tax being payable.