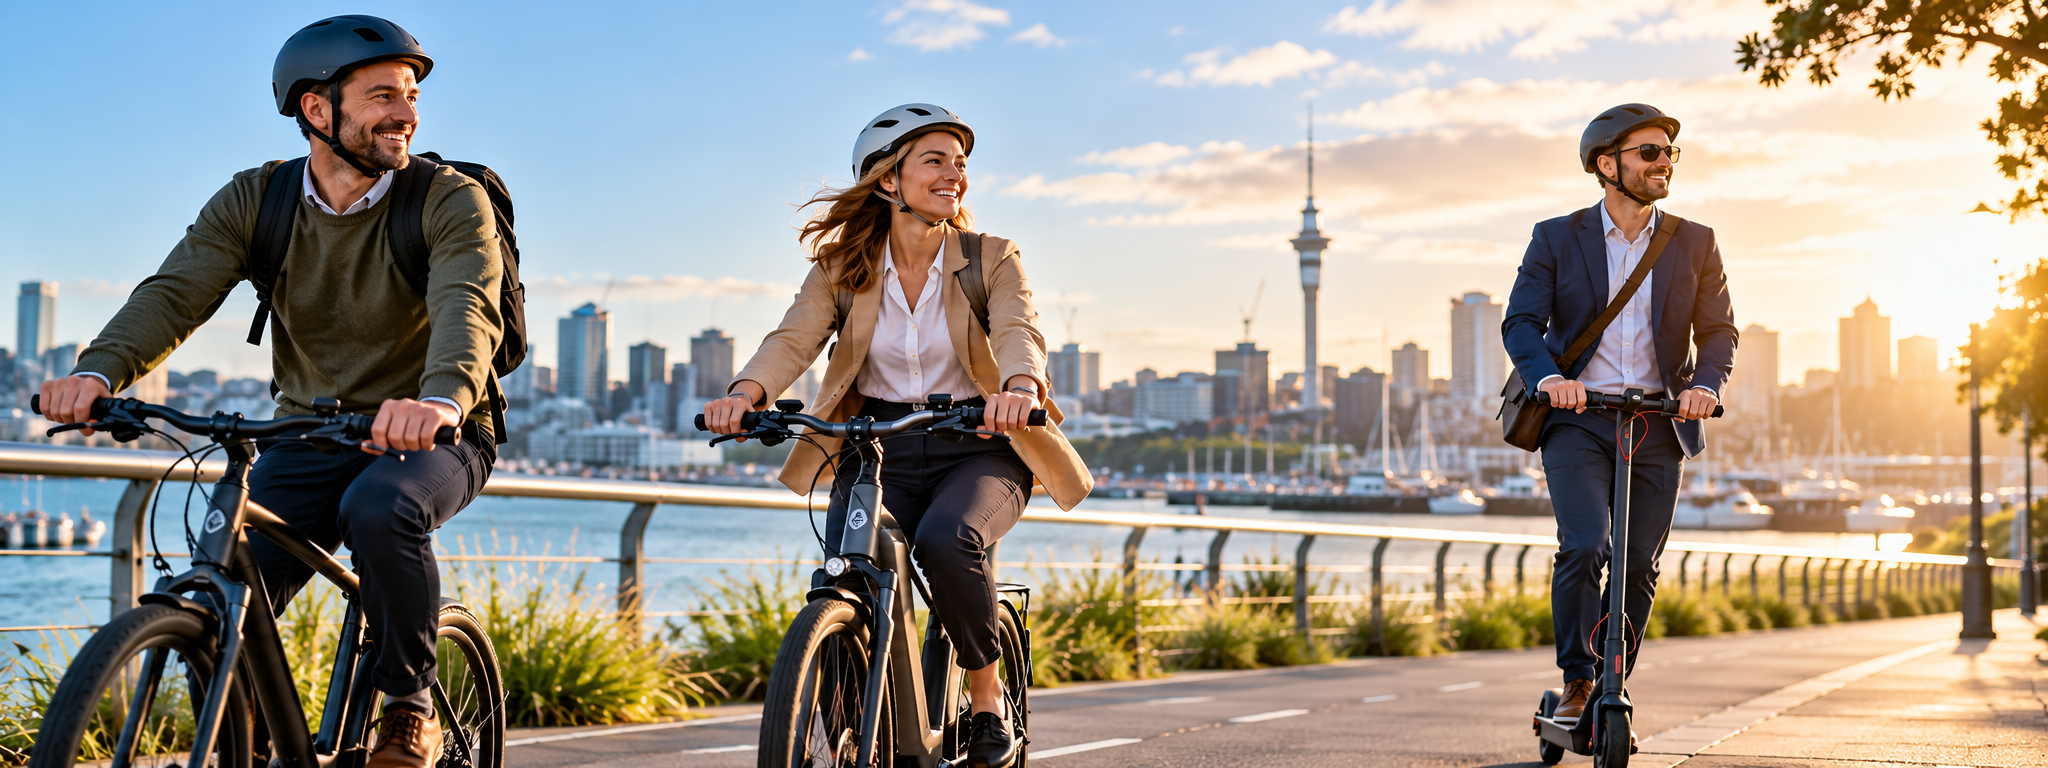
Employers can offer staff a tax-efficient way to purchase or lease bicycles, e-bikes and e-scooters for commuting, with payments made from their pre-tax salary.
There can be worthwhile tax benefits for both the employer and employee. However, salary sacrifice arrangements need to be structured correctly to meet Inland Revenue requirements.
What are the benefits?
When an approved scheme is used:
- The benefit can be exempt from Fringe Benefit Tax (FBT).
- Employees pay from their gross (pre-tax) salary, which may reduce PAYE and other deductions calculated on their salary.
- GST-registered employers may be able to claim back GST on eligible costs.
There are rules to follow
These arrangements need to meet specific requirements. In particular:
- Salary reductions must not reduce an employee’s pay below the applicable minimum wage.
- The salary sacrifice period must not extend beyond the lease period.
- The equipment and arrangement must remain within the limits of the approved programme.
- The employment agreement and payroll treatment need to be set up correctly before deductions begin.
There are Inland Revenue-approved arrangements available, including schemes operating under specific product rulings. Some of these rulings are time-limited, so it is important to check that the arrangement being used is current and compliant.
Employees receiving Working for Families should also consider whether a change to their gross salary could affect their entitlement.
Talk to us first
While these schemes can offer useful tax savings, changing an employee’s remuneration package involves tax, payroll and employment considerations.
If the arrangement is not set up correctly, Inland Revenue may treat the salary deductions as ordinary taxable income, potentially resulting in additional tax being payable.